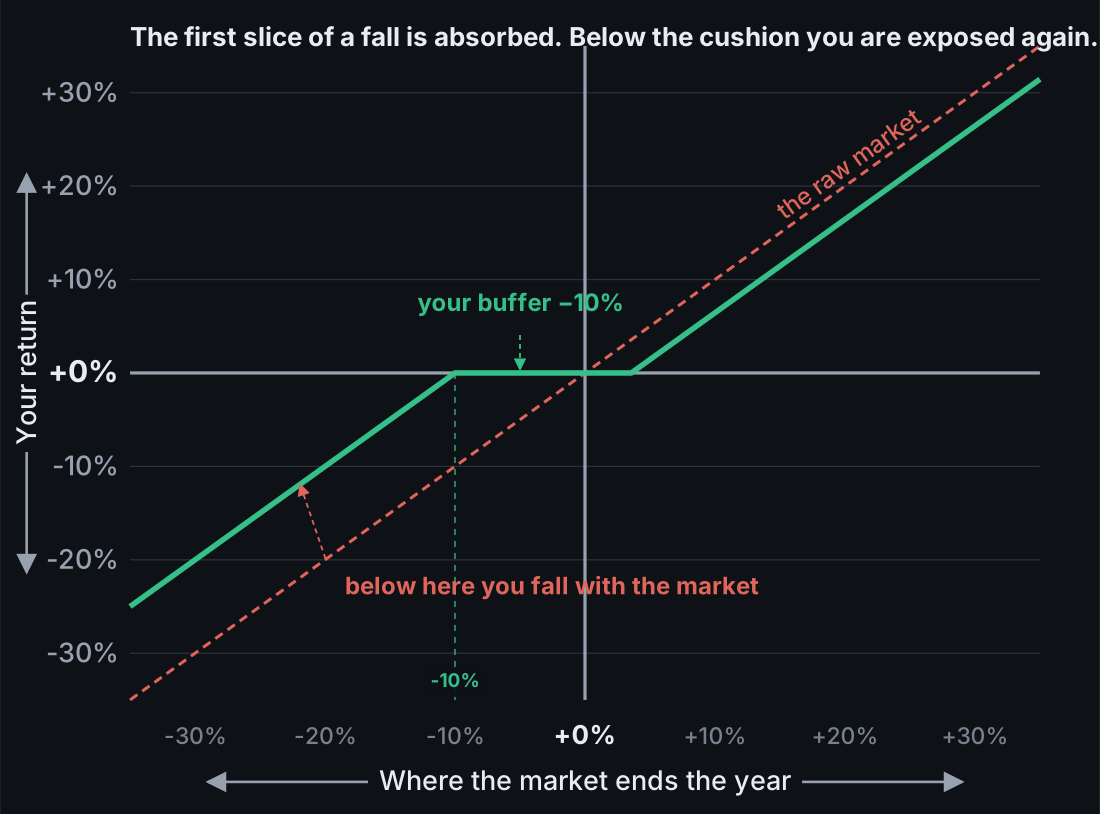
The first slice of any fall is absorbed for you.
Instead of stopping your losses at a floor, the Buffer takes the first part of a decline off your shoulders entirely. Your payoff begins sooner than a floor’s, with the upside uncapped unless you choose a cap.
We buy shares in the index you choose — the S&P 500 or the Nasdaq 100 — and they sit in your own account, in your own name. You own them and you collect the dividends. Then we place the protection around those shares, so it is in place from the first day.
We don’t touch the shares you have. You keep them and you keep the dividends, and because nothing is sold, the gains you’ve been carrying keep deferring. We simply place the protection around what you already hold.
An everyday cushion, not a hard stop. The first slice of any loss is absorbed. Below that you fall with the market again, though you stay ahead of it by the size of your buffer. Your upside is not capped unless you choose a cap. As with the Floor, we build it with cash that is already in your account, and that cash becomes the protection you hold. There is nothing for you to send, buy or sign. We walk one buffer through start to finish at its −10% level, then show you the other levels available.
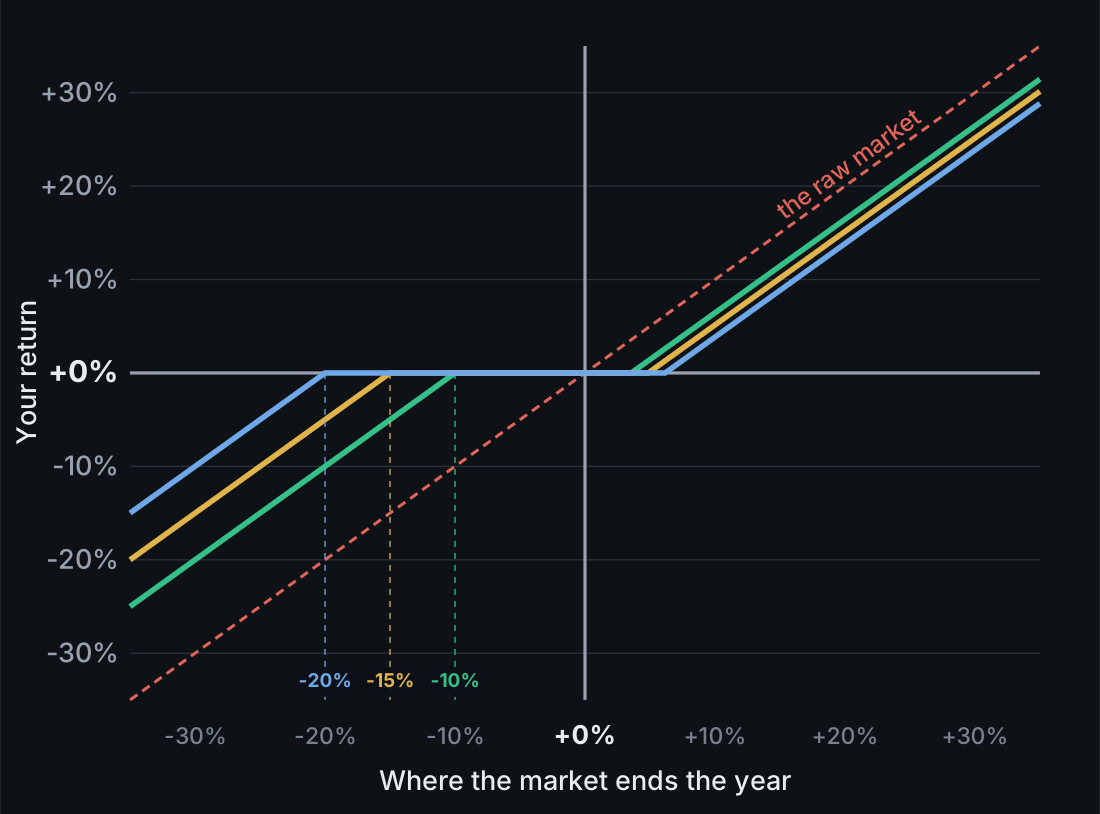
Above the band we sell to pay for the protection, every dollar the market rises is a dollar for you. The line runs parallel to the market, one step below it. Through the cushion you are held level. Only below the cushion do you ride down again. The dashed line is the market on its own.
A Buffer starts paying you sooner than a Floor and protects differently. That difference is the whole decision — here it is without the jargon.
A small piece of the money already in your account — usually a few percent — buys a pair of options (a put spread), and together they cover the whole account for the term you choose. In return, the first part of any rise replaces the money that bought them — after that, the gains are yours.
The market drops and the cushion takes it until it is used up. A Floor stops your losses; a Buffer takes the first slice off you entirely.
Past the cushion you’re exposed again — but every loss is still lighter by the slice already absorbed. A cushion takes less of your money to buy than a floor does, which is why your payoff begins sooner.
The structure is bought outright in the open market, with a small piece of the money already in your account, and it is held in your own name.
A Floor if a hard worst case helps you sleep. A Buffer if you mainly want the ordinary bad years smoothed. Your advisor walks you through both.
Priced against 2016–2026 market and option-chain data. These figures are hypothetical, not an actual account. When the market falls, your buffer absorbs the first slice of it, and when the market climbs back you climb with it.
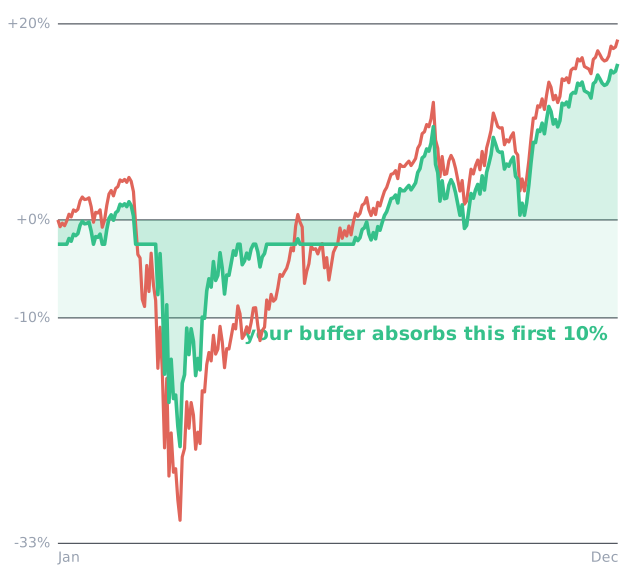
The market fell ~31% in five weeks, then finished the year +18.4% including dividends. Your −10% buffer absorbed the first 10% of that fall. That is why the line falls about ten points less than the market does. A buffer cushions from the top down. It does not stop at −10% the way a Floor does. Below −10% you fall with the market again, but you stay 10% better off than it. You ended the year at +15.9%.
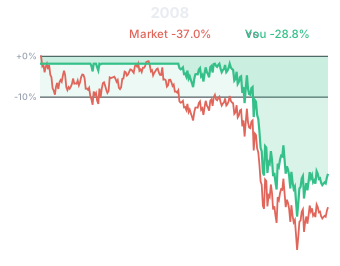
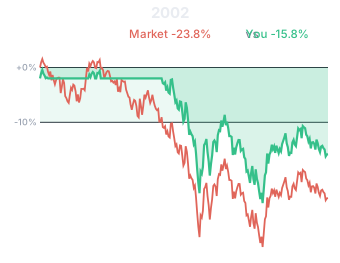
2008 and 2002: real daily S&P 500 data and real option-chain pricing. Benchmarks shown at their calendar-year close, the basis used throughout this site. Notice that 2008 is the one place a Buffer does not flatten the way a Floor does. Inside 2008 the S&P was down about 47% and Vanguard Balanced about 31.9% at their worst points, which is what an investor lived through. But a buffer is defined at the end of its term, so calendar years are what compare like for like.
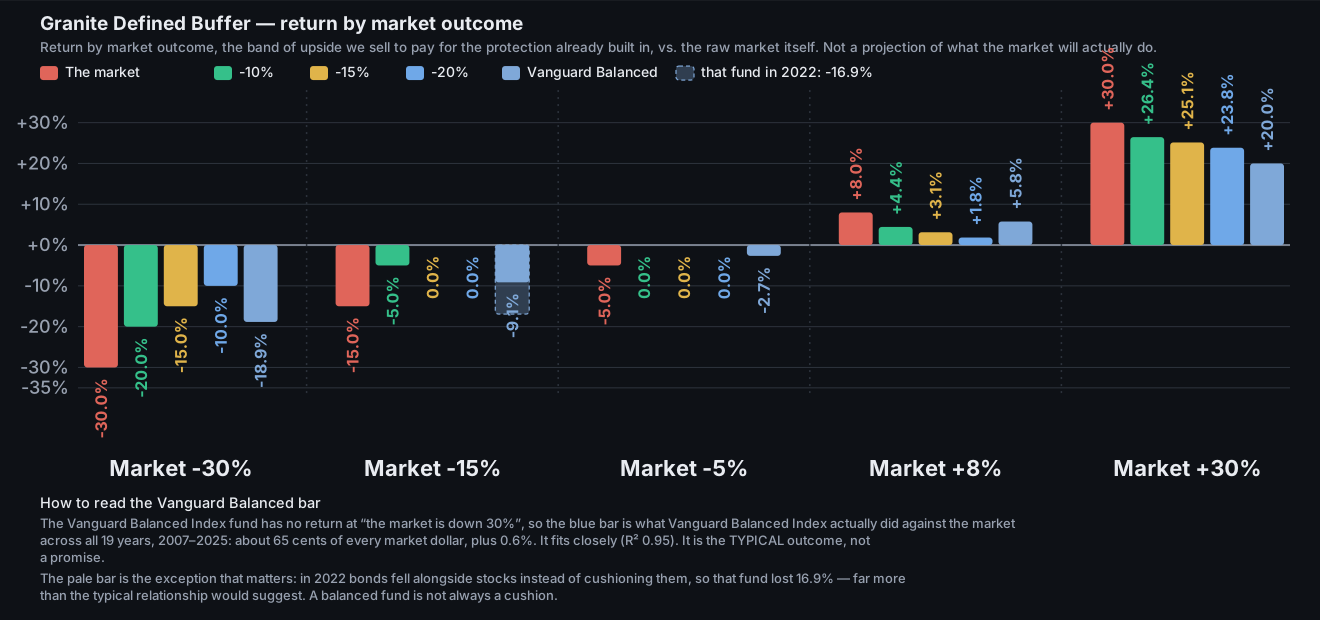
The same five market outcomes, priced from the level where this buffer’s own payoff really starts.
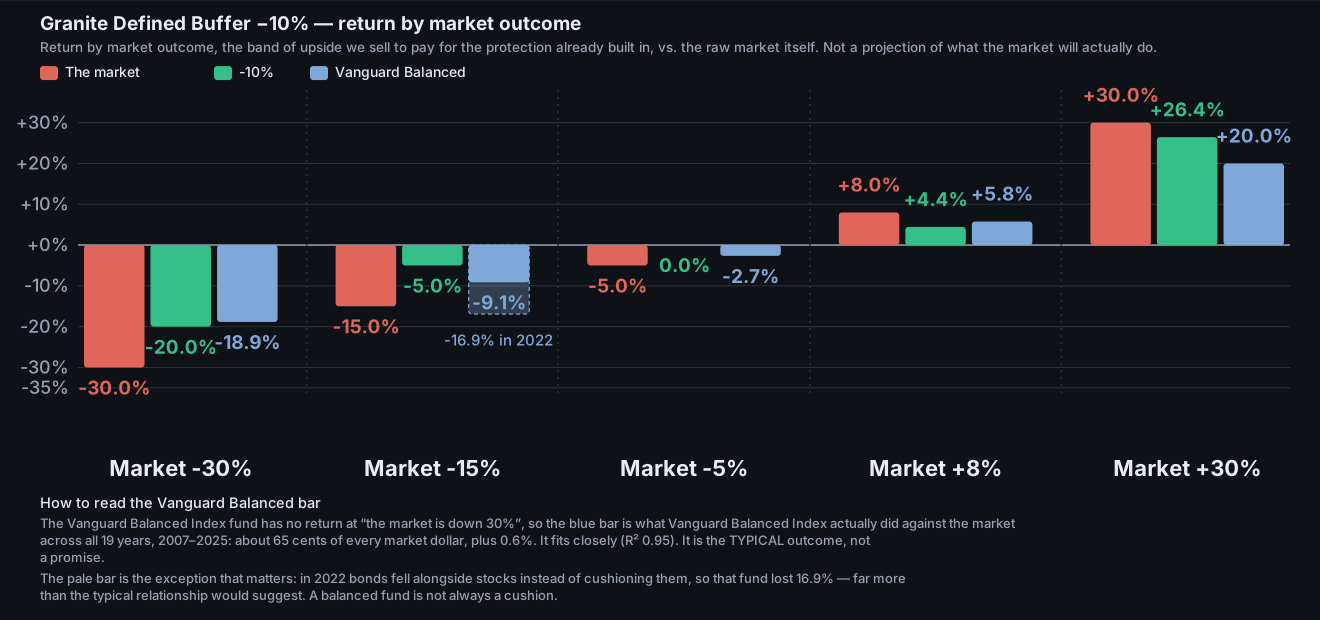
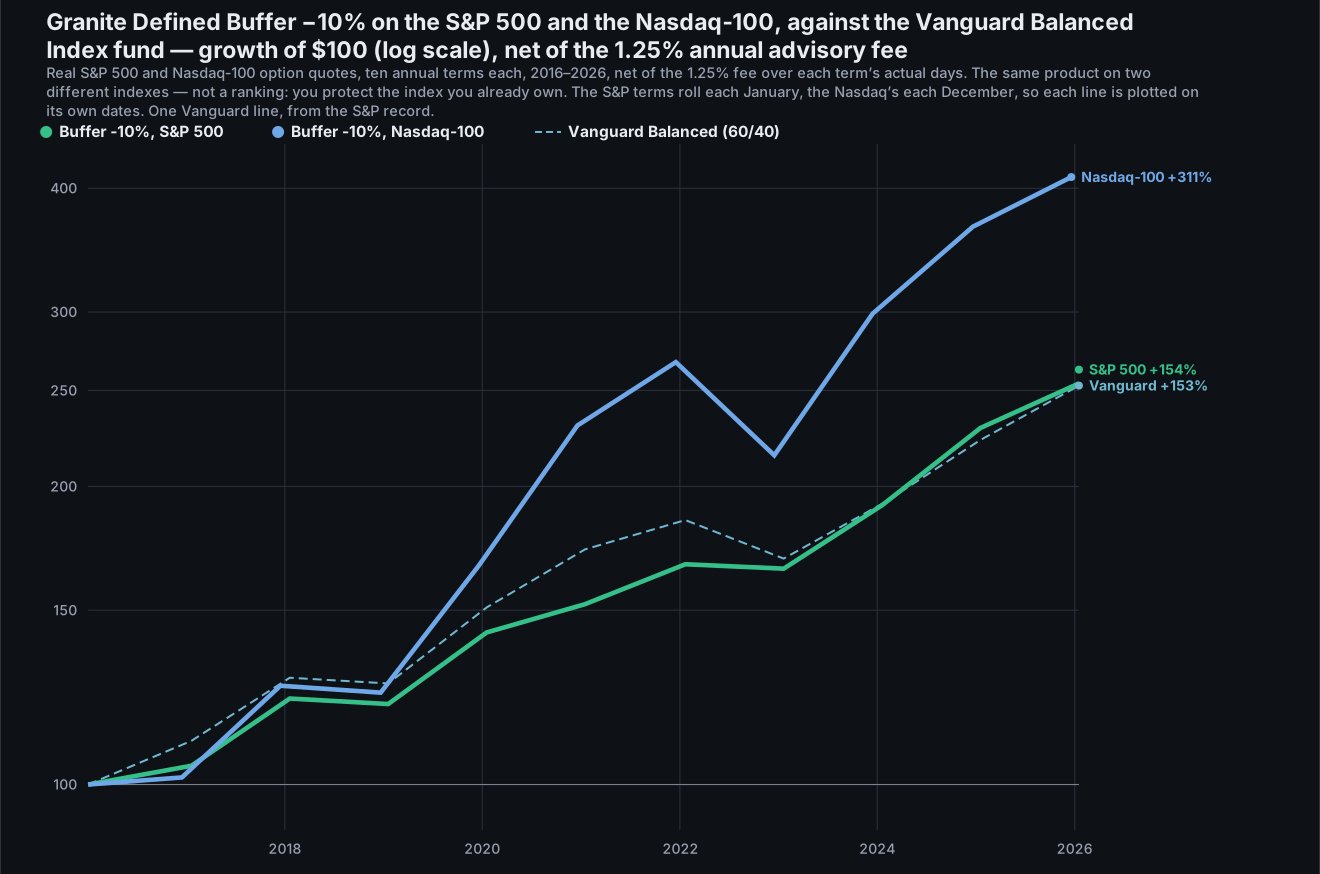
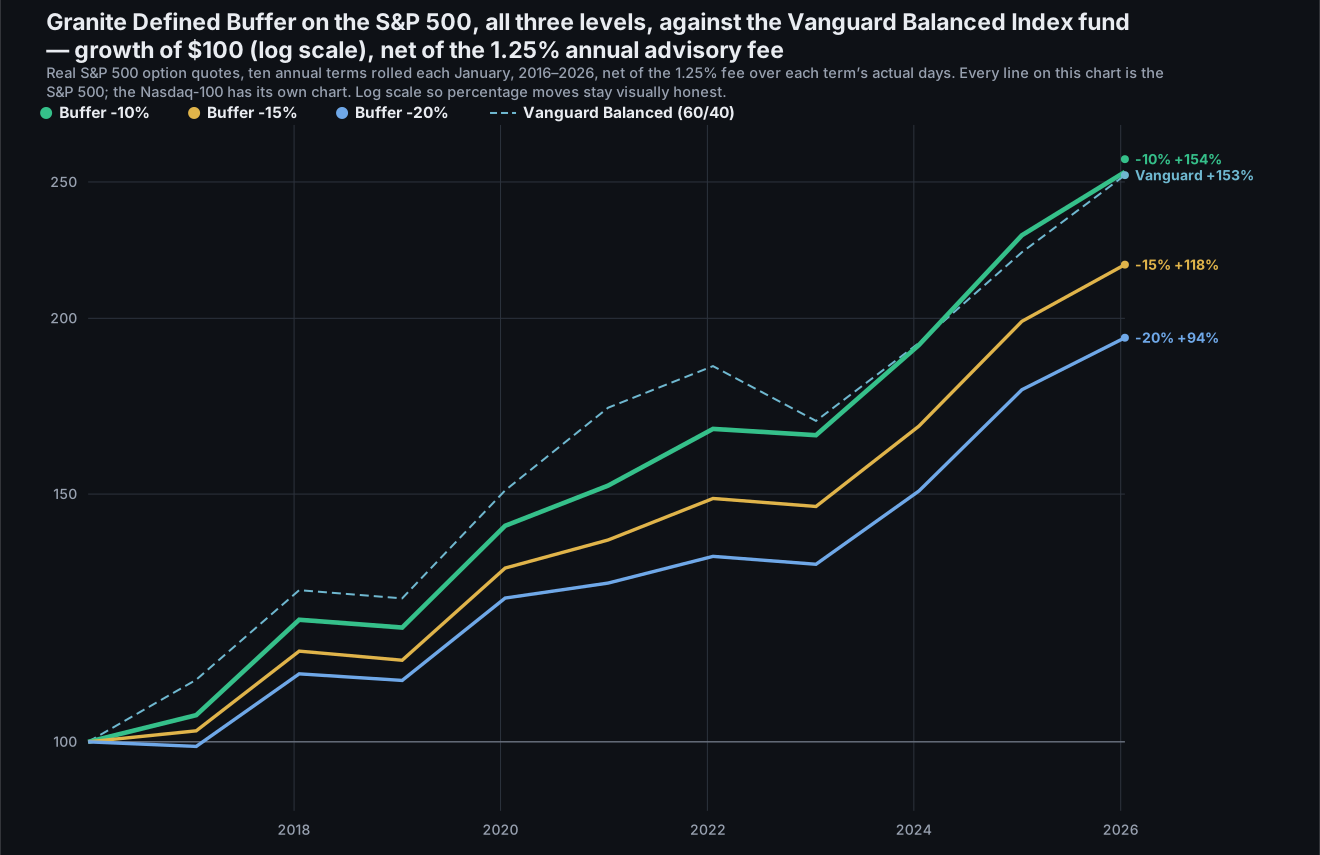
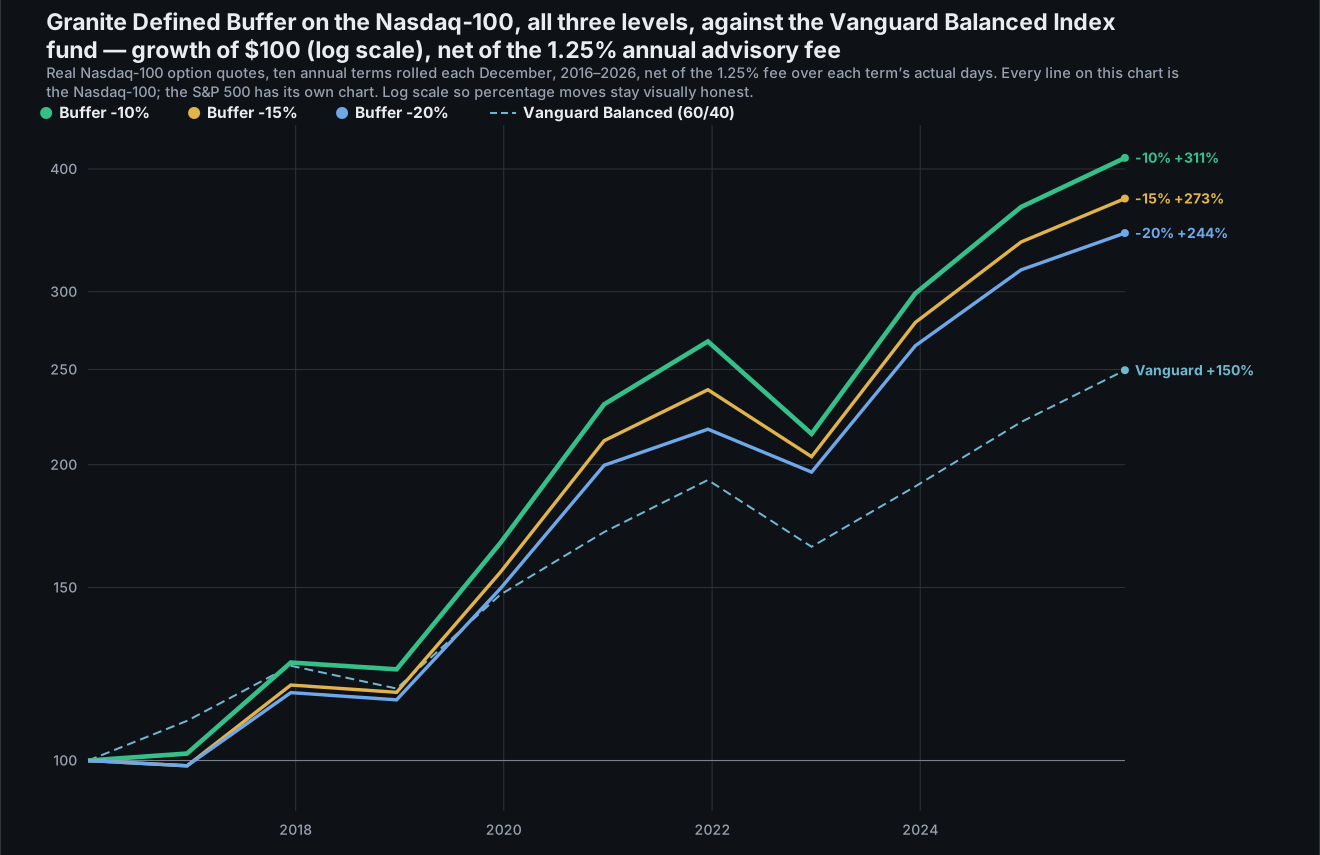
CAGR means compound annual growth rate. It is measured over our published ten-year window: ten annual terms, rolled each January, 2016–2026. All three figures are net of our 1.25% advisory fee, charged over each term’s actual days. Each figure is an average of the twelve start-month ladders’ own growth rates, and all three are worked out the same way, so they can be compared directly. The S&P 500 and Vanguard figures are total returns, with dividends and distributions reinvested. They are taken from the real tracking funds, never from an assumed yield. This window opens in 2016 and therefore does not contain the 2008 crash — and a deep crash is precisely where a Buffer, unlike a Floor, keeps falling below its cushion. It does contain the 2020 COVID crash and the 2022 bear market. We show the 2008 and 2002 panels above precisely because the growth figures here miss them. Hypothetical/backtested: priced on real S&P 500 option prices throughout, with the crash years reconstructed from the option prices of the day. Not actual accounts.
A deeper buffer barely changes where your payoff begins in a normal year, but it softens an ordinary correction a great deal. The trade-off is that in a truly deep crash you still ride down below the cushion.
Look at the −20% buffer: a −5% market and a −15% market both land in the same place, at zero. That’s the cushion at work. Inside the cushion, an ordinary dip and a much worse one both leave you level.
Each small graph shows what one piece is worth at the end of the term. The horizontal axis is the gain or loss on the index; the vertical axis is the gain or loss in your account from that piece. The letter “B” stands for the top of the band — it is not a fixed number; the market sets it on the day we buy. The example uses a −10% buffer.
What it is for: this is your actual investment. Everything below is shaped around it, never instead of it.
What it is for: the bought put at 0% covers a fall from the first dollar — but on its own it would be a full floor at today’s price, far too expensive. Selling the put at −10% hands back the coverage below −10%, and the cash it brings in makes the pair much cheaper than a Floor’s put. What is left covers exactly the first 10% of a fall: you absorb nothing until −10%, then take the loss from there, ten points better off than the market.
What it is for: the sold call brings in cash — enough to pay for the cushion in Step 1. On its own it would hand over all the upside, so the bought call at B is added to switch it off: above B the two cancel exactly. What is left is a fixed-size giveaway — the first rise, from 0% up to B — and nothing else. Why B moves: B is placed wherever the band’s cash exactly covers the cushion’s price that day. When protection is expensive, B sits higher and the band is wider; when it is cheap, B sits lower. So you never spend cash on protection; you trade the first slice of any rise for it instead.
Read it: a modest fall costs you nothing. A deep fall hurts, but ten points less than the market. A modest rise earns nothing — that slice was the price. A strong rise is kept in full, the band’s width behind the market. No cash left your account to buy any of it.
All four option legs are on the index itself, settle in cash, and share one expiry. Each small graph is the picture at expiry and ignores what the leg cost or earned — the band is sized so those balance.
Move the dial, see your exact return at every level of the market, before you invest a dollar. This is the same live calculator as our Design Your Outcome page.
The Buffer is built for a client who expects ordinary dips rather than catastrophes, and who would like the first slice of one absorbed. It is the softer of the two. It improves the common outcome, and it does not stop a severe fall.
The cushion is measured at the END of the term, not day by day. Figures shown are net of our 1.25% advisory fee. These are real listed options, held in your own account and in your own name. Options involve risk and are not suitable for every investor.
A Buffer wins often and small. Its payoff begins sooner and it tracks closer to the market, so it takes the frequent, mild dip far better. A Floor wins rarely and big. It flattens right at the line, so it owns the rare, deep crash. The 2008 panels above show it: a Floor holds near its line where a Buffer of the same depth keeps falling below its cushion.
There’s no wrong answer, only your own appetite for risk. An investor most afraid of a 2008-style event wants the Floor. The Buffer suits an investor who wants a ride closer to the market, and whose payoff begins sooner. It asks one thing in return: below a certain point you are fully exposed to the market again. Many investors use both, and split their money between them.
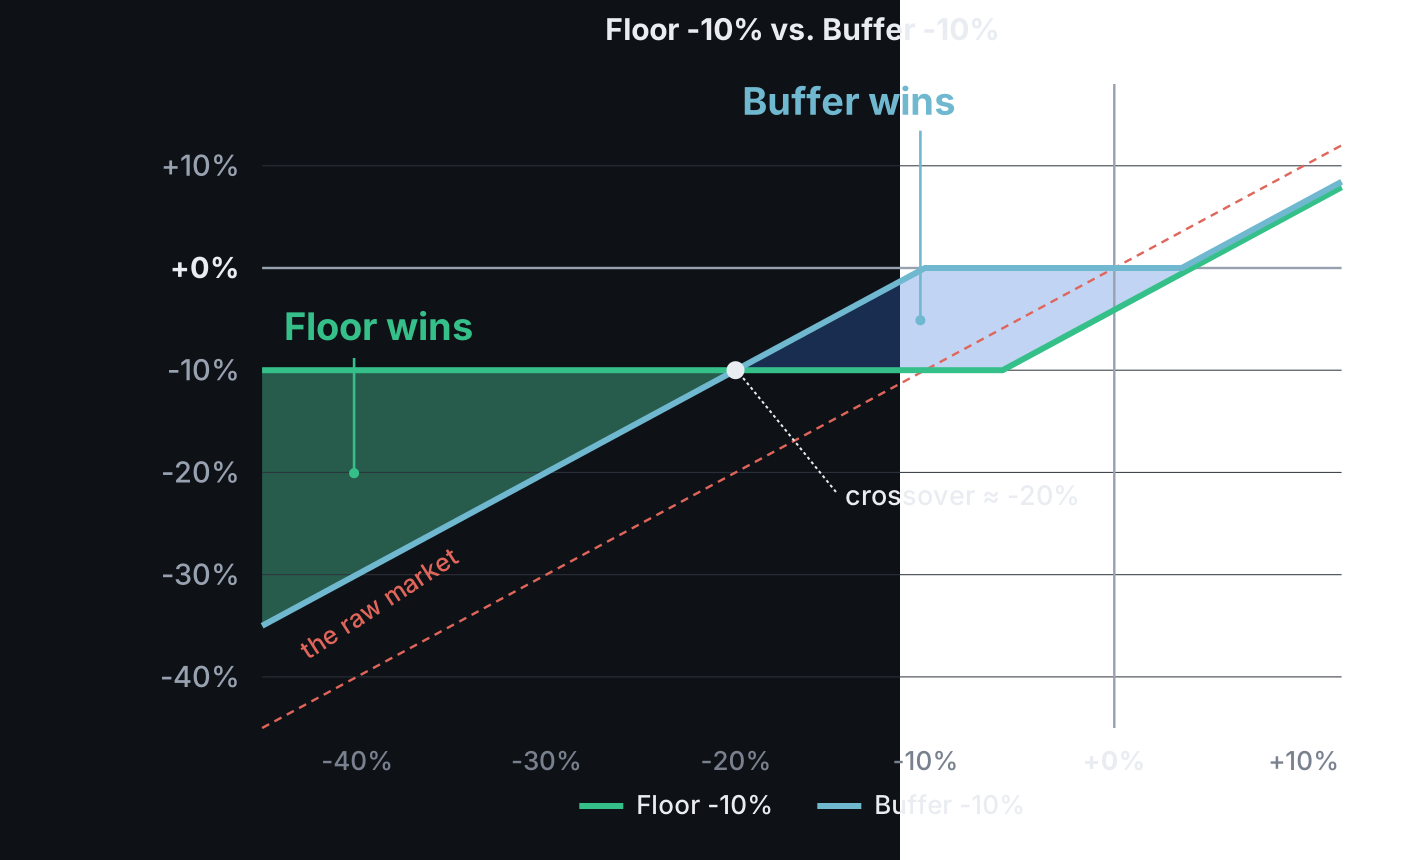
Illustrative payoff diagrams, built from the level where each dial’s payoff really starts. They are not a projection of what the market will actually do.
Tell us how much of a decline you’d want absorbed and we’ll build it around your account, at the size and date you choose.
Schedule an introductory call